September 30, 2026
A Canadian interest-income fund that aims to provde shorter-term growth with reduced volatility.
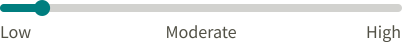
Is this fund right for you?
RISK RATING
How is the fund invested? (as of September 30, 2026)
| Name | Percent |
|---|---|
| Domestic Bonds | 96.1 |
| Cash and Equivalents | 3.2 |
| Foreign Bonds | 0.7 |
| Name | Percent |
|---|---|
| Canada | 99.3 |
| United States | 0.7 |
| Name | Percent |
|---|---|
| Fixed Income | 96.8 |
| Cash and Cash Equivalent | 3.2 |
Growth of $10,000 (since inception)
For the period 07/09/2018 through 09/30/2026 tr.with $10,000 CAD investment, The value of the investment would be $11,581
Fund details
| Top holdings | Percent (%) |
|---|---|
| Quebec Province 2.30% 01-Sep-2029 | 7.0 |
| Canada Government 3.25% 01-Sep-2028 | 4.0 |
| Canada Government 3.00% 01-Sep-2031 | 3.8 |
| Ontario Province 1.35% 02-Dec-2030 | 3.5 |
| Cash and Cash Equivalents | 3.1 |
| Sun Life Financial Inc 2.80% 21-Nov-2028 | 2.9 |
| Toronto-Dominion Bank 3.61% 10-Sep-2030 | 2.6 |
| Federation des Caisses Desjardins du Quebec 3.714% 07-16-2031 | 2.4 |
| Canada Housing Trust No. 1 2.85% 12-15-2030 | 2.4 |
| Alberta Province 2.05% 01-Jun-2030 | 2.2 |
| Total allocation in top holdings | 33.9 |
| Portfolio characteristics | Value |
|---|---|
| Standard deviation | 2.18% |
| Dividend yield | 5.53% |
| Yield to maturity | 3.74% |
| Duration (years) | 2.61% |
| Coupon | 3.29% |
| Average credit rating | A+ |
| Average market cap (million) | $88,570.3 |
Understanding returns
Annual compound returns (%)
| 1 MO | 3 MO | YTD | 1 YR |
|---|---|---|---|
| -0.63 | 0.02 | 0.04 | 0.23 |
| 3 YR | 5 YR | 10 YR | INCEPTION |
|---|---|---|---|
| 4.26 | 1.59 | - | 1.80 |
Calendar year returns (%)
| 2025 | 2024 | 2023 | 2022 |
|---|---|---|---|
| 3.24 | 5.25 | 4.76 | -4.49 |
| 2021 | 2020 | 2019 | 2018 |
|---|---|---|---|
| -1.36 | 4.50 | 2.44 | - |
Range of returns over five years (August 01, 2018 - September 30, 2026)
| Best return | Best period end date | Worst return | Worst period end date |
|---|---|---|---|
| 1.82% | Mar 2025 | 0.45% | Sep 2023 |
| Average return | % of periods with positive returns | Number of positive periods | Number of negative periods |
|---|---|---|---|
| 1.30% | 100 | 39 | 0 |
 fundgrade A+ logo
Fund category
Canadian Short Term Fixed Income
Inception date
July 09, 2018
Management expense ratio (MER)*
1.17%
(December 31, 2024)
Fund management
Mackenzie Investments
Net assets (million)
$12.3
Price
$11.58
Number of holdings
168
Minimum Investment
$500
Fund codes
FEL — CLGB018A
Contact information
Customer service centre
Toll free: 1-888-252-1847
Corporate website
Q2 2026 Fund Commentary
Commentary and opinions are provided by Mackenzie Investments.
Market commentary
Canada’s economy stayed under pressure in the second quarter as trade uncertainty continued to weigh on business confidence, though the labour market showed signs of stabilizing. Employment picked up in May, and the unemployment rate eased to 6.6%. Inflation accelerated, with the annual pace rising to 3.2% in May from 2.8% in April, as higher gasoline prices linked to the conflict in the Middle East pushed up energy costs. Core inflation measures held closer to 2%.
The Bank of Canada (BoC) held its policy rate at 2.25% at both its April and June meetings, its fourth and fifth consecutive holds. The BoC said it was looking through the temporary effect of higher energy prices while watching for signs that price pressures were becoming more persistent, and it pointed to risks on both sides from the trade dispute with the U.S. and the energy shock.
The Canadian fixed income market rose over the second quarter. The yield on the 10-year Government of Canada bond eased late in the period, falling below 3.40% by late June, its lowest level in more than three months, as contained core inflation supported expectations that the BoC would leave rates unchanged. Government bond prices firmed as yields declined. Corporate bonds were broadly stable, and energy-sector issuers benefited from firm oil prices early in the quarter. High-yield bond prices were choppy but finished the quarter higher.
Performance
Overweight exposure to Canadian corporate bonds contributed to performance because of their coupon income and solid earnings. Their additional yield helped to offset volatility in government bonds.
Canadian government bond futures positioning detracted from performance. Changing inflation and interest rate expectations led to higher volatility across the government bond yield curve.
Portfolio activity
ARC Resources Ltd. (3.465%, 2031/03/10) was added for its Montney assets, cash generation and manageable debt. Shell PLC’s proposed acquisition of it improved future creditor support. Province of Alberta (2.05%, 2030/06/01) was increased for its duration (interest rate sensitivity). Despite a weaker budget outlook, Alberta has a lower debt burden and higher economic capacity, supporting its longer-term credit quality.
Royal Bank of Canada (5.01%, 2033/02/01) was sold after strong share price performance. The Bank of Nova Scotia (2.62%, 2026/12/02) was reduced as the bond approached maturity. Proceeds were redeployed into securities with greater income or capital-appreciation potential, while maintaining diversified exposure to Canadian financial issuers.


Summary
For the period 07/09/2018 through 09/30/2026 with $10,000 CAD investment
Total returns performance
15.81%

Last price
$11.58 CAD
as of market close 09/30/2026
Value of $10,000 investment
$11,581.39 CAD


